
Why America’s Auto Industry Is Recalculating Its North American Strategy
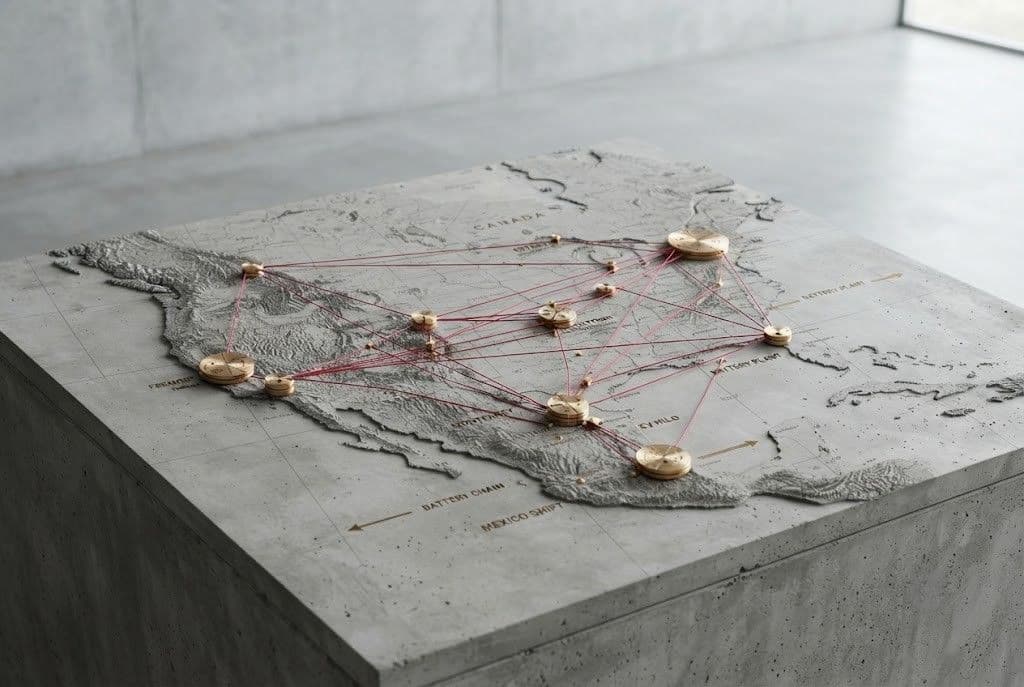
For decades, the U.S. auto industry treated North America less as three separate manufacturing markets than as a single production system. Vehicles and components routinely cross the U.S., Canadian and Mexican borders as companies balance labor costs, supplier networks, plant capacity and access to consumers.
That model is now being reassessed.
The immediate pressure comes from a sharp deterioration in U.S.-Canada trade relations. On August 24, President Donald Trump threatened to raise tariffs on Canadian-made cars, trucks and automotive parts to 50% from January 1, 2027, after U.S.-Canada trade negotiations broke down. Canada has indicated that it could respond with further tariffs of its own.
For automakers, however, the problem is larger than one tariff rate. The deeper question is whether the economic logic that made North American integration attractive can still be relied upon.
An integrated system under pressure
The North American auto industry did not emerge by accident. The transition from the Canada-U.S. Auto Pact to NAFTA and eventually the United States-Mexico-Canada Agreement encouraged companies to organize production across borders. Mexico became an important manufacturing base, while Canada retained major assembly and component operations and the United States remained the region’s largest vehicle market and a critical manufacturing hub.
USMCA reinforced regional sourcing. Its automotive rules require 75% regional value content for light vehicles and core parts to qualify for preferential treatment, alongside labor-value and North American steel and aluminum requirements.
The economic advantage was straightforward: companies could specialize without abandoning the regional market. A component could be manufactured in one country, processed in another and assembled into a vehicle somewhere else, with the resulting efficiencies outweighing the costs of moving goods across borders.
That calculation becomes less attractive when every border crossing carries greater policy risk.
Tariffs change the investment equation
The proposed Canadian tariffs illustrate the problem. Ford, General Motors and Stellantis have significant Canadian operations, while Canadian plants also supply vehicles and components to the U.S. market. Ford, for example, has committed billions of dollars to its Oakville, Ontario, facility, where production plans include Super Duty pickups.
Moving such production into the United States is possible in principle, but it is not equivalent to moving a warehouse. Assembly plants require specialized equipment, trained workers, supplier relationships and years of capital planning. Existing U.S. factories may also lack spare capacity.
The result is a tension between policy objectives and industrial economics. Tariffs can make domestic production relatively more attractive, but they can simultaneously raise the cost of vehicles if companies cannot quickly replace foreign capacity.
Honda has already warned that continued U.S.-Canada trade friction could force higher vehicle prices and has said uncertainty over trade rules is affecting its decision about a potential additional North American assembly plant.
For consumers, the mechanism is relatively direct: higher component or vehicle costs can reduce manufacturers’ margins, encourage price increases or cause companies to redesign sourcing strategies. For workers, the effects are more uneven. New U.S. investment could create manufacturing jobs, while production reductions elsewhere in North America could threaten existing employment.
Mexico becomes more important—and more complicated
Mexico presents a different strategic calculation.
Its lower manufacturing costs, established supplier ecosystem and proximity to the U.S. market have made it an important part of the regional auto industry. But Washington is now pushing for stricter rules governing how much of a North American vehicle must actually originate in the United States.
Reuters reported in May that the Trump administration was seeking an 82% North American content threshold, with half of that value potentially required to come from the United States. Those proposals remain part of negotiations rather than settled policy.
For automakers, such rules could fundamentally alter sourcing decisions. A Mexican plant may remain economically efficient, but if the vehicle loses preferential market access because too much of its value comes from outside the United States, the calculation changes.
Mexico is therefore not simply competing with the United States on wages. It is competing within a regulatory framework whose definition of “North American” may itself be changing.
That uncertainty is particularly significant as the three countries reconsider USMCA. Washington declined in July to extend the agreement for another 16 years, beginning a process of annual reviews while the existing agreement remains in force. Automotive rules of origin are expected to be among the most difficult issues.
A more regional supply chain may not mean a purely American one
The likely response from automakers is not necessarily to abandon Canada and Mexico. Instead, companies may build greater redundancy into their networks.
That could mean sourcing more critical components domestically, maintaining alternative suppliers, increasing U.S. assembly capacity and designing vehicles around multiple production locations. It could also mean shifting investment toward facilities that can serve several models or powertrain configurations.
Such resilience comes at a cost. Duplicating suppliers or production capacity can reduce the efficiency gained from specialization. Companies must therefore decide how much insurance against trade disruption is worth paying for.
Investors face the same trade-off. A plant built primarily to minimize labor and logistics costs may offer attractive economics under stable trade rules. A more expensive U.S. facility may become more valuable if tariffs and regulatory uncertainty persist. Capital allocation is consequently becoming a question not only of cost, but of policy durability.
The broader competitive landscape adds another variable. U.S. officials are increasingly concerned about Chinese automotive content entering North American supply chains, while Chinese manufacturers are expanding their presence in Mexico and other international markets. That makes the geographic origin of components a strategic issue as well as a commercial one.
The next North American model
Several outcomes remain possible.
A negotiated settlement could preserve much of the existing production network while imposing somewhat tighter sourcing requirements. A more fragmented trade regime could encourage greater U.S. production but raise costs and reduce some of the efficiencies created by regional specialization. Automakers could also maintain a mixed model, with high-value or strategically sensitive components increasingly produced in the United States while Mexico and Canada remain important manufacturing bases.
The decisive variables will be the final tariff structures, the outcome of USMCA negotiations, consumer demand, labor costs, factory capacity and the pace at which companies can redirect investment.
The important shift is therefore not simply from “globalization” to “reshoring.” It is from assuming that North American integration will remain stable to treating geography as a strategic risk variable.
America’s auto industry spent decades optimizing where each stage of production should occur. It is now having to optimize for something harder to measure: the possibility that the rules governing those decisions may change again.